What Financial Mistakes Do Women Entrepreneurs Make Because Money Does Not Feel Emotionally Safe?


When Money Doesn’t Feel Safe: The Financial Decisions Women Founders Make From Fear
There is a version of financial advice that assumes money is neutral: See the numbers. Make the rational decision. Move on. Easy.
Except money is rarely just math. Money can represent safety, freedom, power, responsibility, control, approval, failure, proof that you made the right decision—or proof that maybe you did not.
When money does not feel emotionally safe, even an exceptionally skilled founder can make financial choices that contradict what she logically knows:
- She can know she needs to hire, yet continuously delay the job offer.
- She can maintain significant cash reserves and still experience intense anxiety every time she approves an operational expense.
- She can recognize her prices need to increase, yet find herself offering discounts anyway.
- She can avoid reviewing financial reports because she already feels behind.
- She can pay the team, the contractors, the software subscriptions, and the taxes—while her own compensation remains entirely optional.
This is not because women are inherently worse with money. They are not.
Research on entrepreneurship repeatedly demonstrates that women operate inside financial environments where confidence, self-promotion, risk, and access to capital are evaluated differently. A landmark study on startup funding revealed that venture investors were significantly more likely to ask female founders questions focused on preventing losses (prevention orientation), while male founders were asked questions focused on achieving gains (promotion orientation). Other behavioral research shows that women describe equivalent performance less favorably than equally performing men in self-promotion settings.
So this conversation is not “Why are women so emotional with money?” Absolutely not.
The far more useful question is: What financial behaviors develop when money becomes associated with uncertainty, judgment, scarcity, or loss? Those behaviors often begin as protective mechanisms; they just don’t always produce good business outcomes.
💡 TL;DR: Emotional Safety & Financial Systems
- The Core Issue: Financial anxiety can cause founders to avoid financial data, over-save out of fear, or swing between extreme restriction and reactive spending.
- The Manifestations: Avoiding the numbers, holding excess idle cash at the expense of growth, underpricing services, paying everyone except yourself, and managing entirely from today’s bank balance.
- Self-Trust & Systems: Research links higher financial self-efficacy (the belief that your actions affect financial outcomes) with proactive financial management and lower long-term distress.
- The Solution: True financial safety isn’t created by avoiding risk; it’s created by building systems—forecasts, reserve targets, tax strategies, and pricing floors—that give you the clarity to lead calmly.
Financial Behavior Matrix: Protective Pattern vs. Financial Strategy
When money doesn’t feel emotionally safe, founders often deploy protective behaviors that feel responsible in the short term but create long-term operational drag:
| Protective Behavior | Short-Term Emotional Payoff | Long-Term Operational Drag | Financial Infrastructure Fix |
Avoiding Financial Reports | Temporary relief from uncomfortable numbers. | Discovered cash shortages become sudden crises; delayed strategic adjustments. | Predictable cadence (e.g., weekly 20-min cash review, monthly financial sync). |
Extreme Cash Hoarding | Sensation of maximum safety and control. | The founder becomes the cheapest labor; capacity bottlenecks strangle growth. | Categorized reserves (Operating Reserve, Tax Reserve, Growth Capital). |
Paying Yourself Last | Sensation of hyper-responsibility to the team. | Founder burnout; business model remains artificially subsidized and unsustainable. | Structured owner compensation tied to entity mechanics (W-2 + draws). |
Bank-Balance Management | Immediate clarity on today’s liquid balance. | Reactive panic during temporary lulls; inability to see incoming collections or liabilities. | 13-week rolling cash-flow forecast and dynamic scenario modeling. |
7 Financial Mistakes Driven by Emotional Safety Needs
Mistake #1: Avoiding the Numbers Until Something Forces You to Look
You know your revenue, you know roughly what is in the bank, and you know when payroll lands. But deeper strategic questions keep getting postponed: What was our actual net profit last quarter? How much is reserved for taxes? Can the business truly carry this new hire?
A 2023 study examining financial anxiety found that participants with high financial anxiety were substantially more likely to avoid financial tasks than those with lower anxiety. The researchers also noted a strong negative association between financial anxiety and proactive money-management behavior.
Financial avoidance offers short-term relief, but the cost is time. A cash shortfall identified 12 weeks in advance is a minor planning exercise; a cash shortfall identified three days before payroll is a crisis.
Mistake #2: Over-Saving Because Spending Feels Dangerous
Maintain a strategic cash reserve is vital, but there is a distinct difference between holding intentional reserves and keeping a business financially constipated.
You can have $300,000 sitting idle in checking and still make decisions from scarcity—delaying necessary software, postponing key hires, and treating marketing as an indulgence. Eventually, the founder becomes the cheapest source of labor in the business, solving every capacity bottleneck with “I’ll just work more hours.”
Money sitting in an account requires clear labels:
- Operating Reserve (e.g., 3 months of fixed overhead)
- Committed Tax Capital
- Working Capital
- Growth Capital
Once every dollar has an assigned job, spending shifts from “Do I feel safe letting this money go?” to “Does this investment match our capital allocation plan?”
Mistake #3: Underinvesting in the Business Out of Fear of Being Wrong
Sometimes the underlying fear isn’t losing the money—it’s the embarrassment of making the wrong choice: What if I hire the wrong agency? What if this system fails? What if people realize I’m figuring this out as I go?
Waiting is still a capital decision. There is an explicit cost to delaying delegation, keeping broken sales processes, or remaining buried in $30-an-hour tasks while leading a multi-million-dollar company.
Research on financial self-efficacy shows that individuals who strongly believe their actions influence their financial future take more proactive steps before adverse events and experience less financial distress afterward. Financial self-trust isn’t believing every decision will be flawless; it’s trusting your ability to adjust based on the data you receive afterward.
Mistake #4: Swinging From Extreme Restriction into Impulsive Spending
This cycle mirrors chronic dieting: restriction, restriction, extreme frugality—followed by burnout and a sudden, reactive purchase (a $15,000 program, an unplanned software suite, an expensive consultant) hoping it provides immediate relief.
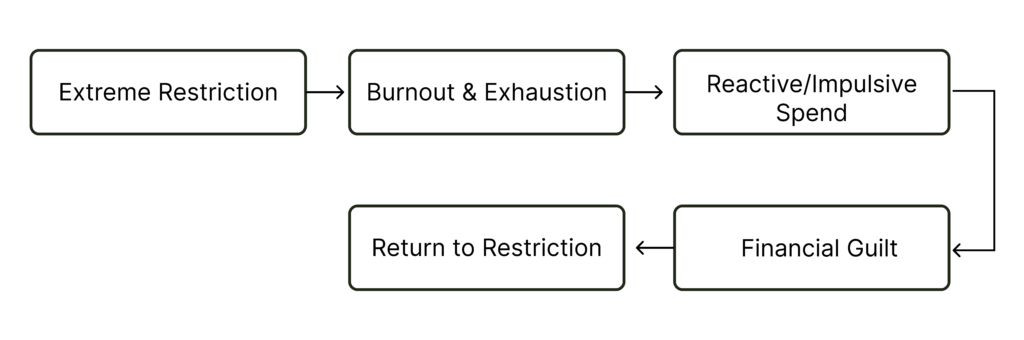
Expansive, strategic investing is not the same as reactive spending. Before making an unplanned major purchase, filter it through three structural questions:
- What specific operational bottleneck am I expecting this money to solve?
- What objective metric will indicate whether this investment worked?
- What happens to our cash runway if the return takes twice as long as projected?
Mistake #5: Paying Everyone Except Yourself
Many women founders treat not taking a paycheck as proof of responsible leadership. Employees, contractors, software vendors, and tax authorities get paid first. Whatever happens to remain (if anything) becomes owner compensation.
Over time, this creates a business model that is artificially subsidized by the founder’s unpaid labor.
How you compensate yourself is an operational and tax calculation dependent on your entity structure:
- Partnerships & Sole Proprietorships: Non-wage owner draws.
- S-Corporations: Shareholder-employees must receive reasonable W-2 wages before taking non-wage distributions, as mandated by the IRS.
- C-Corporations: Formal officer W-2 salaries.
Compensation should not be reinvented emotionally every month. It should be a predictable, built-in operating cost of the enterprise.
Mistake #6: Underpricing Because Charging More Feels Emotionally Risky
In a service enterprise, setting prices can feel deeply personal because you are placing a dollar value on your expertise, judgment, and time.
Compounding this, cultural and social dynamics around self-promotion mean female founders often face subtle friction when asserting pricing power. The fix isn’t trying to resolve your entire relationship with self-worth before sending a proposal—it’s building pricing architecture:
- What are the direct fulfillment and labor costs?
- What gross margin does the enterprise require?
- What overhead capacity does this project consume?
- What is our absolute minimum acceptable pricing floor?
Data creates a structural floor that fear cannot negotiate beneath.
Mistake #7: Making Every Decision From Today’s Bank Balance
Checking your bank app multiple times a day and letting that single number dictate your emotional state creates chaotic leadership:
- $180,000 in checking: “Everything is fine; let’s launch a new initiative!”
- $85,000 in checking: “Cancel spending; we are in trouble!”
The bank balance is a static snapshot. It doesn’t reflect $40,000 in accounts receivable clearing next week, nor does it account for $60,000 in payroll and taxes due ten days later. A rolling 13-week cash flow forecast turns the bank balance from an emotional scoreboard into one data point within a broader financial map.
What Financial Safety Actually Looks Like
Financial safety doesn’t mean zero business risk. Clients will leave, campaigns will underperform, and unexpected expenses will arise.
Financial safety means having enough visibility and structural control that changes don’t send you into reaction mode:
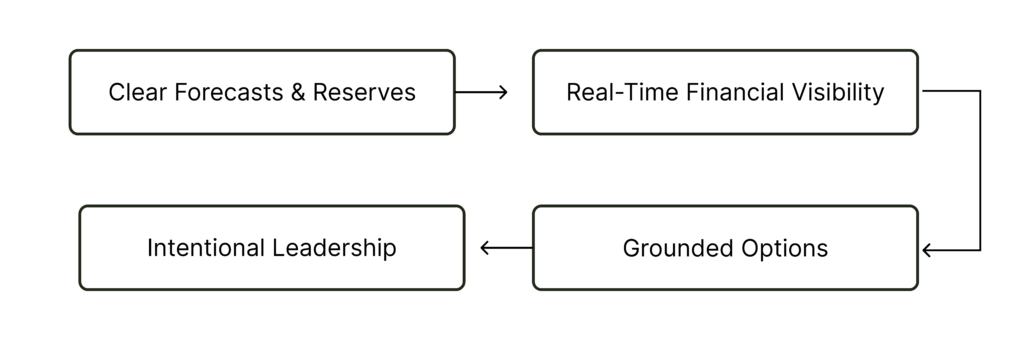
You build financial self-trust quietly: reviewing the numbers when scheduled, transferring tax reserves, paying yourself according to your structure, approving planned investments, and saying no to impulsive ones.
Reflection & Self-Audit
Sit with these questions without judgment:
- When money feels uncomfortable, do I move toward the data or away from it?
- Am I holding idle cash because the business requires it, or because spending causes anxiety?
- What operational investment have I delayed even though the business urgently needs capacity?
- Do I have a predictable, structured method to compensate myself?
- Where am I asking money to make me feel safe instead of building systems that help me lead calmly?
Pattern recognition is the first step toward grounded financial leadership.
Strategic, Shame-Free Financial Leadership at Abundantia Advisory
At Abundantia Advisory, we believe financial management should be strategy-rich and entirely shame-free. You deserve accurate numbers, but you also deserve a strategic advisory relationship that respects the human being making the financial choices.
Our work bridges accounting, tax strategy, cash flow modeling, and executive decision support—helping you build predictable owner-pay structures, 13-week cash forecasts, unit-level margin visibility, and clear reserve targets.
Clear systems create visibility. Visibility creates strategic choices. Intentional choices build unshakeable self-trust.
Ready to build financial systems that support both your business and your leadership?
Connect with Abundantia Advisory →
Disclaimer: This content is provided for general educational purposes only and does not constitute individualized tax, legal, accounting, payroll, investment, financial, or mental-health advice. Business-owner compensation and tax treatment depend on entity structure and individual circumstances. Consult a qualified professional regarding your specific situation.
Leave a Reply


This calendar gives solopreneurs and small biz CEOs a monthly roadmap for compliance, money strategy, and financial self-trust.
Whether you're DIYing or managing a team, this high-value tool helps you:
✅ Hit every IRS and state filing on time
✅ Build CEO habits like money dates and pricing boundaries
✅ Stay calm, confident, and cash-savvy month after month