How Should a Coach or Consultant Pay Herself From an S Corporation?


Designing a Sustainable Owner-Compensation Strategy for Service-Based Founders
There is a specific moment in the life of an S Corporation when the founder pauses and thinks: “Wait. How am I actually supposed to pay myself now?”
Before electing S-Corp status, managing money felt relatively straightforward: client payments hit the bank account, business expenses got paid, and you transferred whatever was left into your personal checking account.
Then you elect S-Corp status, and suddenly:
- Your accountant tells you that you must set up formal payroll.
- Someone else starts talking about shareholder distributions.
- Your tax preparer brings up “reasonable compensation.”
- Internet forums promise a magical “60/40 salary split.”
Suddenly, paying yourself from the company you built feels like an advanced corporate accounting course you never signed up for.
Let’s make this simple. If you own an S Corporation and actively work in the business, you will generally pay yourself in two distinct ways:
- W-2 Wages for the actual labor you perform inside the company.
- Shareholder Distributions (when the business has cash capacity) because you own the enterprise.
These two payment methods are not interchangeable. Building a healthy owner-pay strategy is about far more than minimizing self-employment taxes; it is about engineering a business model that consistently supports the woman who built it.
💡 TL;DR: S-Corp Owner Compensation
- The Employee Mandate: The IRS treats corporate officers performing substantial services as W-2 employees. You must run formal payroll for your labor.
- Reasonable Compensation: Your salary must reflect market value for the actual duties you perform. There is no universal IRS “60/40 rule.”
- Salary vs. Distributions: Salary compensates your labor and triggers payroll taxes. Distributions reflect your equity ownership and avoid self-employment taxes.
- Retirement Impact: 401(k) and SEP-IRA contributions are calculated solely from W-2 wages, not shareholder distributions.
- Cash Flow First: Bank balance does not equal distributable cash. Always reserve funds for payroll, operating capital, and taxes before taking distributions.
Salary and Distributions Are Not the Same Thing
Imagine you own a high-growth coaching or consulting firm. You are the CEO: you sell, you coach, you develop proprietary methodologies, you manage contractors, and you make strategic decisions.
In reality, two distinct roles are occurring simultaneously:
- You are an employee performing operational labor.
- You are an investor/shareholder who owns the equity.
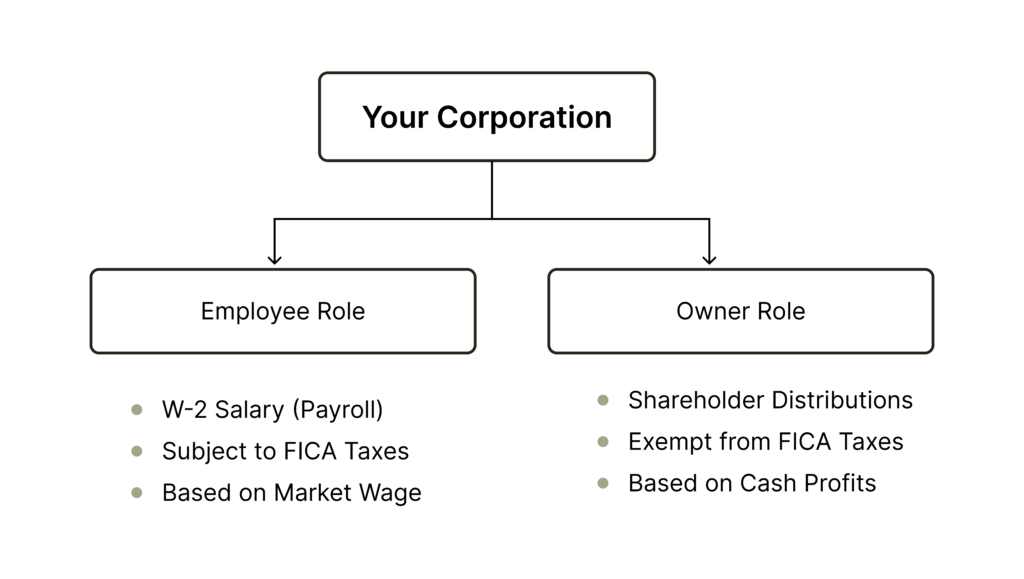
Under IRS guidelines, a corporate officer who performs substantial services is classified as an employee. Owning 100% of the company does not erase that employee relationship.
An active S-Corp owner should never say: “I don’t take a salary; I just transfer money to my personal account whenever I need it.” While that feels simpler, tax authorities classify those un-monitored transfers as misclassified wages, which can trigger severe back payroll taxes, penalties, and interest.
Decision Matrix: W-2 Salary vs. Shareholder Distributions
| Feature | W-2 Salary (Payroll) | Shareholder Distribution |
| Tax Treatment | Subject to Income Tax + FICA (Social Security/Medicare). | Subject to Income Tax; Exempt from FICA taxes. |
| IRS Requirement | Mandatory for active shareholder-employees (Reasonable Compensation). | Optional; depends on excess profits and available stock basis. |
| Retirement Sourcing | Used to calculate 401(k), SEP-IRA, and SIMPLE IRA contribution limits. | Cannot be included in retirement contribution calculations. |
| Payment Method | Processed through formal payroll with automated tax withholdings. | Executed as an owner draw/bank transfer from profits. |
What Does “Reasonable Compensation” Actually Mean?
Reasonable compensation depends entirely on the specific duties you perform inside your company. The IRS does not publish a static chart stating that a $500,000 consulting firm requires an exact $80,000 salary. Instead, tax authorities evaluate your specific facts and circumstances (governed by Revenue Ruling 74-44):
- Key Duties: What specific tasks do you handle daily?
- Time & Effort: How many hours per week do you devote to the business?
- Skill & Experience: What training, credentials, and track record do you bring?
- Comparable Wages: What would you have to pay an independent manager or specialist in your geographic market to replace your duties?
- Revenue Sourcing: How much revenue is created directly by your personal coaching/consulting services versus administrative, contractor, or automated systems?
The Coach/Consultant Nuance
If your consulting firm generates $600,000 in gross revenue and you personally pitch every client, deliver all the consulting hours, write the methodology, and manage the operations, your personal labor is the primary driver of that income.
That requires a very different reasonable salary calculation than owning a $600,000 firm where a team of associate coaches handles 90% of client delivery while you spend five hours a week on high-level oversight. Same revenue, but vastly different operational roles.
Dismantling the “60/40 Rule” Myth
You may have heard advisors suggest: “Just pay yourself 60% salary and 40% distributions.”
While rules of thumb are occasionally used as conversation starters, current IRS guidelines do not recognize any fixed salary-to-distribution percentage. An arbitrary ratio cannot account for whether you work 10 hours or 60 hours a week, whether your firm generated $150,000 or $2,000,000, or whether your personal expertise is the sole service product being sold.
The IRS expects a documented, defensible compensation rationale based on market data rather than a generic ratio found on social media.
A 3-Step System for Paying Yourself
Instead of improvising your pay every month, establish a structured operational rhythm:
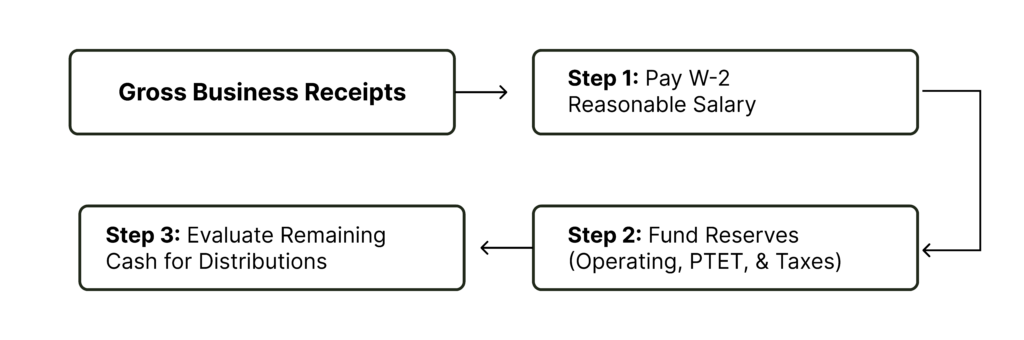
Step 1: Establish Your Baseline W-2 Salary
Work with your CPA to set a defensible, market-based salary for your role. Put that number on automated, consistent payroll (weekly, biweekly, or monthly). Your salary becomes a standard operating cost of the business, giving you a predictable personal baseline.
Step 2: Protect Corporate Liquidity & Reserves
Before taking distributions, ensure the business retains adequate capital for its upcoming liabilities:
- Vendor and contractor payables
- Software and operational overhead
- State Pass-Through Entity Tax (PTET) and federal tax reserves
- An emergency operating reserve (e.g., 3 months of fixed expenses)
Cash in the bank is not automatically distributable cash. Having $100,000 in your checking account does not mean you have $100,000 available to distribute if $35,000 is earmarked for upcoming payroll, $25,000 belongs to tax reserves, and $20,000 represents your operating reserve floor.
Step 3: Execute Planned Shareholder Distributions
Once your W-2 salary is funded and corporate reserves are protected, remaining cash profits can be distributed to you as an owner. Establish a clear policy (e.g., evaluating distributions at the end of every quarter) rather than transferring money randomly whenever checking balances look high.
The Founder Is Not the Company’s Emergency Fund
A common pattern among female founders is treating their own compensation as the ultimate variable expense: employees, contractors, software, rent, and tax bills get paid on time, but if cash feels tight, the founder immediately skips her own paycheck.
While short-term sacrifices happen in entrepreneurship, making this your permanent operating model creates a dangerous distortion. It masks underlying profitability problems. If your business only appears profitable because you work for free, the business model is flawed—it is being artificially subsidized by your unpaid labor.
Tax Mechanics: FICA Caps, PTET, and Retirement Limits
Payroll Taxes and the 2026 Wage Base
W-2 wages incur FICA payroll taxes (Social Security and Medicare):
- Social Security: 6.2% employer + 6.2% employee (12.4% total) up to the 2026 wage base cap of $184,500.
- Medicare: 1.45% employer + 1.45% employee (2.9% total) on all wages, with no cap.
Taking distributions for profits above your reasonable salary avoids the 12.4% Social Security and 2.9% Medicare tax on those distribution dollars. However, this tax efficiency must exist within IRS reasonable compensation boundaries, not in place of them.
State Pass-Through Entity Tax (PTET)
In 36+ states, S-Corporations can elect to pay state income taxes at the entity level via PTET. This allows business owners to bypass the federal $10,000 cap on State and Local Tax (SALT) deductions, turning state tax payments into fully deductible corporate expenses.
The Retirement Plan Catch
Your W-2 salary directly dictates how much you can invest in tax-advantaged retirement accounts. Contributions to a Solo 401(k), SEP-IRA, or SIMPLE IRA are calculated strictly from Box 1 / Box 5 W-2 wages. Shareholder distributions cannot be included in retirement plan calculations. Unreasonably suppressing your W-2 salary can severely limit your ability to build long-term wealth outside the business.
Common S-Corp Owner-Pay Mistakes to Avoid
- Taking Distributions Without a W-2 Salary: Running owner draws while taking zero W-2 salary as an active officer is a major audit trigger.
- The “December Cleanup” Trap: Trying to figure out your entire annual salary in a single December payroll run distorts monthly reporting and cash management.
- Draining Corporate Liquidity: Taking aggressive distributions without accounting for quarterly estimated taxes or upcoming overhead leads to liquidity crunches.
- Ignoring Stock Basis Limits: Distributions are only tax-free up to your available stock basis. Taking distributions that exceed your basis triggers taxable capital gains.
Reflection: Building a System That Pays You First
Ask yourself these diagnostic questions:
- Am I running regular, automated W-2 payroll for myself?
- Is my current salary backed by market data for my actual operational role?
- Do I know how much corporate reserve is required before taking a distribution?
- Am I maximizing my retirement contributions based on my W-2 wage strategy?
- Have I built a business that supports me, or am I constantly sacrificing my pay to support the business?
Your labor has value. Your ownership equity has value. A healthy S-Corporation pay strategy honors both while protecting the cash flow of the company.
Strategic Owner Compensation at Abundantia Advisory
At Abundantia Advisory, we believe owner compensation should never be reduced to finding the absolute lowest salary you can get away with. We help coaches, consultants, and service-based founders build integrated financial systems that coordinate reasonable compensation, tax strategy, retirement planning, PTET elections, and cash reserves.
Stop negotiating with your bank account every month. Let’s design an owner-pay strategy that provides personal wealth, tax efficiency, and business stability.
Ready to design an owner compensation structure tailored to your S Corporation?
Connect with Abundantia Advisory →
Disclaimer: This content is provided for general educational purposes only and does not constitute individualized tax, legal, accounting, payroll, investment, or financial advice. Reasonable compensation determinations, state PTET elections, stock basis calculations, and tax obligations vary based on individual facts and circumstances. Consult a qualified professional regarding your specific situation.
Leave a Reply


This calendar gives solopreneurs and small biz CEOs a monthly roadmap for compliance, money strategy, and financial self-trust.
Whether you're DIYing or managing a team, this high-value tool helps you:
✅ Hit every IRS and state filing on time
✅ Build CEO habits like money dates and pricing boundaries
✅ Stay calm, confident, and cash-savvy month after month