What Does a Healthy Profit Margin Look Like in a Service Business?


Written by Megan Munsell, CPA | Published October 14, 2026
On this page
- The Bottom Line on Healthy Profit Margins
- Which Profit Margin Are We Talking About?
- Gross Margin: Does the Service Itself Work?
- Operating Margin: Does the Business Model Work?
- Net Profit Margin: What Is Actually Left?
- What Do Industry Benchmarks Say?
- 8 Factors That Alter What “Healthy” Looks Like
- How to Diagnose Margin Leaks
- 3 Real-World Margin Profiles
- Diagnostic Checklist for Business Owners
Tell me your service business has a 20% profit margin and I am probably going to respond with: “Okay. Tell me more.”
I know—it’s a very annoying CPA answer. But 20% by itself does not tell me whether your business is healthy. Neither does 10%, and neither does 30%.
A solo consultant with almost no delivery costs should not have the same margin as a twenty-person agency. A coaching company selling group programs has completely different economics from a consultancy where every engagement requires senior labor. A mature company distributing cash to its owner has different priorities from a business intentionally hiring ahead of growth.
A company showing a beautiful 40% net profit because the founder works sixty hours a week without paying herself a fair market wage isn’t nearly as profitable as the P&L suggests.
So when someone asks, “What is a good profit margin?” the better question is: “Is this business creating enough margin to support how it operates, where it is going, and what its owner needs it to produce?”
TL;DR: The Bottom Line on Healthy Margins
There is no universal “healthy” profit margin for every service business. Industry benchmarks provide context, but they are starting points, not commandments.
Your ideal margin depends on:
- What it costs to deliver your work
- How your team is structured
- How you price your services
- How much founder labor is buried inside the delivery
- What you are currently reinvesting in
- What the business needs to produce after operational costs
A healthy business generates enough economic value to support operations, market-rate owner compensation, planned growth, taxes, cash reserves, debt obligations, and sustainable owner wealth.
Most importantly: Profit is not the same thing as cash. You must track both.
First: Which Profit Margin Are We Talking About?
Comparing your business to a generic internet benchmark often leads to bad decisions because different margins answer completely different operational questions.
[ Top-Line Revenue ]
         │
         ├── Less: Direct Delivery Labor & Software
         │
         ▼
[ Gross Profit ] ──► Answers: "Does the service itself work?"
         │
         ├── Less: Sales, Marketing, Admin & Overhead
         │
         ▼
[ Operating / Net Profit ] ──► Answers: "Does the entire business model work?"
1. Gross Margin: Does the Service Itself Work?
Gross margin looks at what remains after paying the direct costs of delivering your service.
Revenue−Direct Delivery Costs=Gross Profit
Gross Margin=RevenueGross Profit×100
For a service company, direct costs include delivery employees, client-facing contractors, project-specific software, or direct commissions.
Example: If you sell a $10,000 engagement and direct delivery costs are $4,000, your gross profit is $6,000 (60% Gross Margin). That $6,000 remains to cover marketing, admin, leadership, software, rent, professional support, and net profit.
2. Operating Margin: Does the Business Model Work?
Operating margin evaluates what remains after paying the expenses required to run the company: administrative staff, marketing, sales, leadership, technology, insurance, rent, and office overhead. It reveals whether the entire operating infrastructure is sustainable.
3. Net Profit Margin: What Is Actually Left?
Net profit margin takes you down to the bottom line. However, business structure and owner compensation dramatically affect this number:
- Sole Proprietorships: Owner pay is not deducted as a W-2 expense on Schedule C, inflating reported net margin.
- S-Corporations: Active owners must receive reasonable W-2 compensation (The IRS states that an S corporation must generally pay reasonable compensation to shareholder-employees for services before making non-wage distributions.), which is expensed on the P&L before net margin is calculated.
- Pass-Through Taxation: S-Corp and Partnership owners pay personal income tax on business net income regardless of whether that cash was actually distributed to them.
When someone says, “My net margin is 18%,” the immediate follow-up question must always be: “What owner compensation and tax structure are built into that 18%?”
What Do the Industry Benchmarks Say?
Benchmarks are useful diagnostic tools, but they should inform your strategy, not dictate it:
| Service Business Category | Typical Gross Margin | Typical Net Profit Margin | Key Economic Driver |
| Solo Consulting / Advisory | 70% – 90% | 30% – 50%+ | Low overhead; highly dependent on founder time. |
| Boutique Agencies & Services | 50% – 60% | 15% – 25% | Balanced team structure; requires project management. |
| Full-Service / Scaled Agencies | 40% – 50% | 10% – 20% | Higher administrative, sales, and middle-management overhead. |
| Broad Business Services (Public) | 35% – 45% | 7% – 12% | High volume, lower unit margins, heavy infrastructure. |
These ranges are directional benchmarks, not universal targets. Margin expectations vary significantly by business model, company size, delivery structure, accounting treatment, and growth stage. Broader industry margin data can provide context, but your own economics should determine what “healthy” looks like.
8 Factors That Alter What “Healthy” Looks Like
Factor #1: Your Delivery Model Changes Everything
In service businesses, labor is the product. Unlike software, you cannot sell the exact same hour of labor to 10,000 clients. If every new $10,000 in revenue requires $7,000 in new delivery labor, scaling top-line revenue will not automatically fix a weak profit margin.
Factor #2: Revenue Can Grow While Margins Deteriorate
Growing revenue from $1.5 million to $2 million often requires hiring middle management, expanding scope, or taking on lower-margin clients. If top-line revenue increases by $500,000 but delivery costs increase by $520,000, growth is destroying business value.
Factor #3: Founder Labor Can Hide True Delivery Costs
If a consulting firm reports $500,000 in revenue, $300,000 in expenses, and a “40% net margin” ($200,000), but the founder personally handles sales, delivery, strategy, and management without drawing a market-rate salary, the 40% margin is an illusion. Part of that “profit” is simply unpaid labor.
CFO Insight: To understand the true economics of a founder-led business, calculate what it would cost to hire employees to replace the founder’s daily operational work. A healthy model remains profitable after market-rate delivery labor is paid.
Factor #4: Pricing Dictates Your Operational Headroom
When scope creeps from $10,000 in labor up to $13,000 on a $20,000 fixed-fee contract, your gross profit drops from $10,000 (50%) to $7,000 (35%). The team is busier, the client may be happy, but your margins are eroded. Busyness is not a profitability metric.
Factor #5: Team Structure Alters Baseline Expectations
Moving from a solo operator model to an agency model introduces overhead: payroll taxes, benefits, software seats, administrative support, and unbilled capacity. Margins may temporarily compress during this shift while building delivery capacity.
Factor #6: Low Margins Can Be Strategic (If Given a Job)
Intentionally reinvesting profit into senior leadership, new technology, or geographic expansion can temporarily reduce operating margins from 20% down to 10%. This is healthy—provided the margin reduction has a specific timeline, clear KPIs, and expected revenue returns.
Factor #7: Tax Bills Are Not the Same as Poor Profitability
Pass-through entity owners owe income tax on their share of net business profits regardless of whether that profit stays in the company bank account. Owning a tax debt because your business made money is a cash management issue, not a delivery failure.
Factor #8: Accrual Profit Is Not Liquid Cash
A P&L statement records revenue when earned and expenses when incurred. It does not reflect:
- Delayed client payments (Accounts Receivable expansion)
- Debt principal repayments
- Capital expenditure / equipment purchases
- Quarterly owner tax distributions
A business can show strong accrual profitability on paper while facing a severe liquid cash shortage.
How to Diagnose Margin Leaks
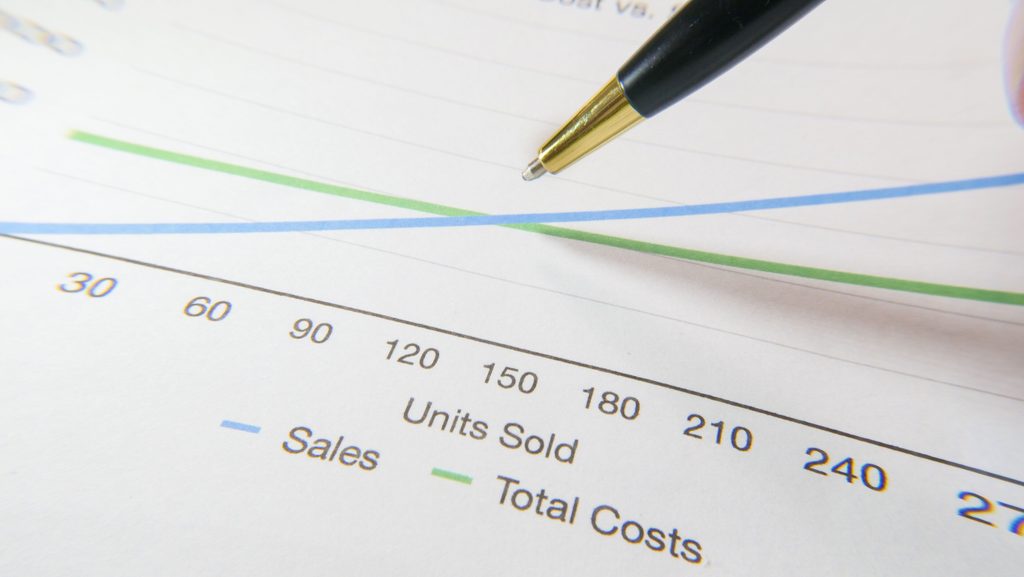
If your books are accurate but you’re still struggling to understand what is driving your margins or what decisions to make next, your business may have outgrown bookkeeping alone.
               [ Is Your Net Profit Underperforming? ]
                                  │
         ┌────────────────────────┴────────────────────────┐
         ▼                                                 ▼
[ Check Gross Margin First ]                     [ Check Operating Overhead ]
• Are delivery hours tracked?                    • Is administrative payroll bloated?
• Is scope creeping without add-ons?            • Are software tools unmonitored?
• Are contractor costs too high?                 • Is sales/marketing CAC rising?
• Is client pricing too low?                     • Is office / facility rent too high?
3 Real-World Margin Profiles
Profile A: The Solo Consultant
- Revenue: $600,000/year
- Model: Highly specialized, minimal overhead, small contractor team.
- Margin Benchmark: A healthy model should yield 35%–50%+ net margin after paying the founder market wages. A 10% margin here signals severe underpricing or excessive overhead.
Profile B: The Scaled Agency
- Revenue: $3,000,000/year
- Model: 20 employees, account managers, sales team, physical/remote infrastructure.
- Margin Benchmark: 50%–60% gross margin and 15%–20% net profit margin. Lower net percentages are acceptable here because the business infrastructure generates revenue independently of the founder’s hours.
Profile C: The Reinvesting Firm
- Revenue: $2,000,000/year
- Model: Intentionally hiring two senior directors to prepare for a $4M scale-up.
- Margin Benchmark: Operating margin temporarily drops from 22% to 11%. This is healthy because the leadership team is built to unlock higher future capacity.
Diagnostic Checklist for Business Owners
Run through these eight questions during your next financial review:
- Does the company generate a meaningful net return for ownership beyond W-2 wages?
- Do you track Gross Margin separately from Net Profit Margin?
- Do you know the exact delivery labor cost for each service line?
- Does your pricing support the team overhead required to fulfill the contract?
- Is founder labor factored into delivery costs at market rates?
- If margins are depressed due to reinvestment, do you have a clear recovery timeline?
- Are accrual profits converting into predictable liquid cash reserves?
- Can the business fund tax obligations without emergency borrowing?
Ready to Build a Financial Architecture That Supports Real Growth?
Stop guessing whether your profit margins are healthy. Partner with Abundantia Advisory to analyze your service economics, fix margin leaks, optimize owner compensation, and build a predictable financial model.
Schedule Your Financial Strategy Consultation Today
Frequently Asked Questions
There is no single profit margin that is healthy for every service business. The right margin depends on your delivery costs, pricing, team structure, founder involvement, overhead, reinvestment plans, taxes, and growth stage. A useful benchmark should provide context, but your own business economics ultimately determine whether a margin is sustainable.
A 20% margin may be healthy for one service business and inadequate or unusually high for another. For example, a founder-led consulting company with minimal overhead may reasonably expect a different margin than a larger agency with employees, account managers, sales staff, and administrative infrastructure. The percentage needs to be evaluated alongside how the business actually operates.
Gross margin measures how much revenue remains after the direct costs of delivering your services. Net profit margin looks at what remains after operating expenses and other costs are accounted for. Gross margin helps evaluate whether the service itself is economically viable, while net margin provides a broader view of the overall business model.
Revenue growth can require additional employees, management, software, sales expenses, or delivery capacity. If those costs grow faster than revenue, the company can generate more sales while becoming less profitable. That is why revenue growth should be evaluated alongside margins rather than in isolation.
Owner compensation can significantly affect how profitable a business appears. In founder-led service businesses, it is useful to consider the market value of the work the founder performs. If the owner is doing substantial delivery, sales, management, or operational work without appropriate compensation, reported profit can overstate the true economics of the business.
Profit and cash measure different things. A business can report accounting profit while cash is tied up in unpaid invoices, debt repayments, equipment purchases, tax payments, or other uses that do not appear the same way on the profit-and-loss statement. For this reason, service businesses should monitor both profitability and cash flow.
Start by identifying where the margin is being lost. Review delivery labor, scope creep, pricing, contractor costs, administrative payroll, software expenses, sales and marketing costs, and unbilled capacity. Improving margins is not always about cutting expenses; it can also involve better pricing, service design, capacity planning, or operational efficiency.
Profit margins should be reviewed regularly as part of the company’s financial reporting process and whenever the business makes meaningful changes to pricing, staffing, services, delivery structure, or growth plans. Looking at margin trends over time is usually more useful than evaluating a single month in isolation.
Megan Munsell is a CPA and fractional CFO with nearly 20 years of experience working with businesses ranging from small businesses to Fortune 50 organizations. Through Abundantia Advisory, she helps founders build stronger financial systems, improve profitability, plan for taxes, and make growth decisions with greater financial clarity.
Disclaimer: This content is provided for general educational purposes only and does not constitute individualized tax, legal, accounting, payroll, investment, or financial advice. Profitability benchmarks vary significantly by industry, company size, accounting treatment, owner compensation, growth stage, and business model. Consult qualified professional advisors regarding your specific circumstances.
Leave a Reply


This calendar gives solopreneurs and small biz CEOs a monthly roadmap for compliance, money strategy, and financial self-trust.
Whether you're DIYing or managing a team, this high-value tool helps you:
✅ Hit every IRS and state filing on time
✅ Build CEO habits like money dates and pricing boundaries
✅ Stay calm, confident, and cash-savvy month after month